What happens behind the scenes when a cross-border payment uses stablecoins, and how much of that should the customer need to understand?
In this episode of Tech Talks Daily, I speak with Shah Ramezani, co-founder and CEO of Noah, about the infrastructure that connects stablecoins to business payments. The discussion goes beyond the transfer itself to the practical work required to move between currencies, choose a route, verify identities, and reconcile the result.
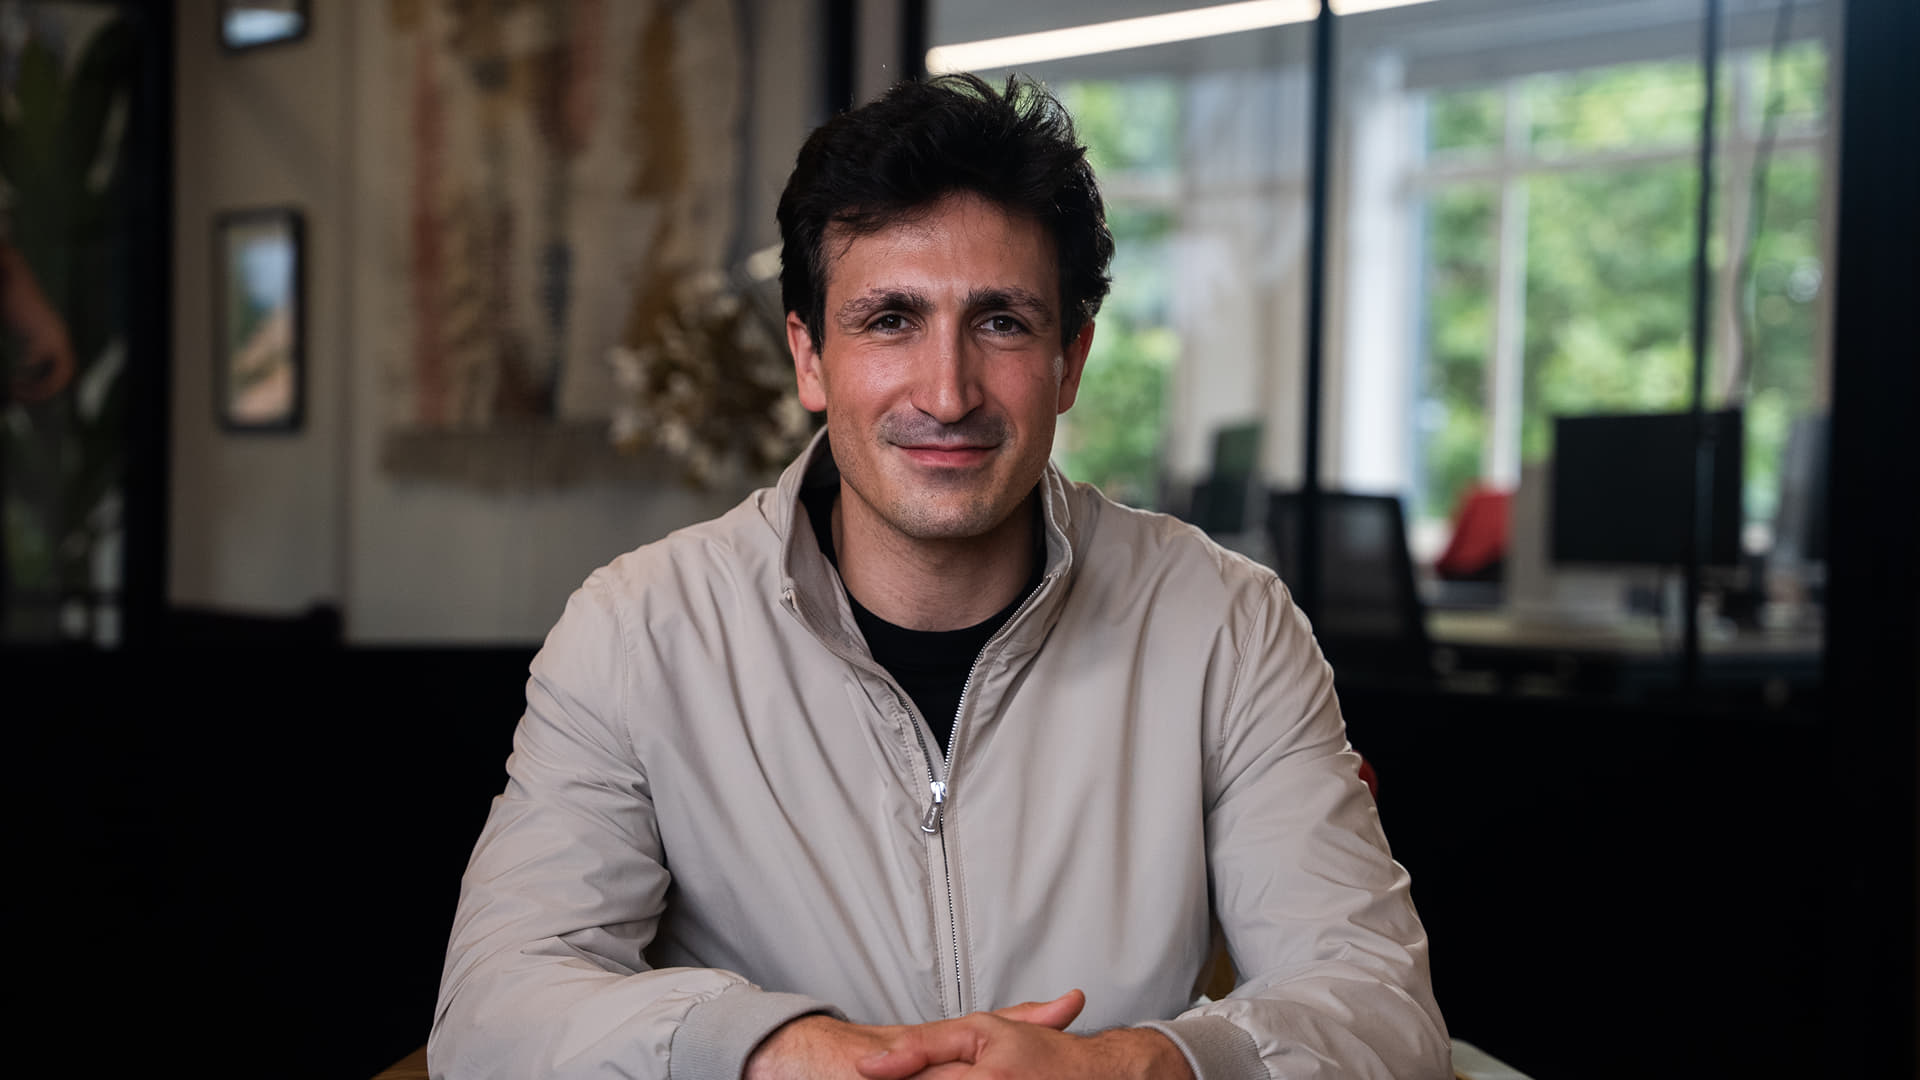
Shah starts with the friction he sees in correspondent banking and the opportunity for a different settlement layer. He explains how stablecoins can move quickly between participants and then connect to local payment methods at either end. His example of a payment from the United States to Argentina helps explain the choices involved, including whether the recipient wants local currency or a dollar-denominated stablecoin. It is an illustrative scenario rather than a named customer case or a universal comparison of costs and delivery times.
I ask what makes that experience work technically. Shah breaks the process into liquidity, routing, compliance, settlement, and reconciliation. The available partner, customer type, destination, and pricing can all affect how a payment is handled. Noah's role, as he describes it, is to bring those components together so partners can connect without building every part themselves.
Identity is another part of the conversation. Shah discusses know-your-customer and know-your-business checks, including arrangements in which partners rely on checks performed by Noah and receive the information they need. His account makes clear that reducing repeated document requests requires coordination among the organizations involved. It also raises questions about who is responsible for each step and how that responsibility changes across markets.
One idea I found most interesting is that users may encounter stablecoin infrastructure without choosing to hold or handle stablecoins themselves. Shah describes payments in which the technology operates behind a familiar interface. For a business considering that approach, the useful comparison is the full payment journey, including conversion, local payout, support, and each participant's obligations.
We also discuss banks' continuing role. Shah rejects the idea that they disappear and instead describes a different distribution of responsibilities across payment networks and financial institutions. The conversation gives listeners a way to consider how new settlement technology can coexist with established banking relationships.
Trust and regulation remain part of that assessment. Shah argues that stronger regulation provides reassurance, while acknowledging the difficulty of serving customers across jurisdictions with different reporting obligations, identity requirements, and fraud patterns. His confidence in the market's direction is his perspective. It should not be read as a guarantee that every stablecoin, provider, or transaction carries the same protections.
Finally, Shah discusses Noah's plans to broaden its capabilities and invest in product development and hiring. He describes an opportunity to make the payment experience simpler and less complex for the user. For me, the accompanying question is how providers make their responsibilities clear when the underlying process spans several organizations.
I would love to hear your thoughts, so please share your experiences. When you assess a new payment route, how do you weigh speed and cost against clarity about responsibility, access to funds, and help when something goes wrong?
Useful Links
[00:00:00] Your agentic AI might not be secure even with real-time data and proper guardrails. But Denodo makes sure your business has every avenue covered. By placing all your data platforms under one AI data layer, your business can reach semantic consistency safely and securely. So get your agents on the same page by visiting denodo.com.
[00:00:26] And you can learn more about how to start trusting your agents to make business decisions. But now, back to today's guest. What has to happen behind the scenes before a payment can move across borders in seconds? Stablecoins are often described as a faster way to send money.
[00:00:49] But the payment, that still needs liquidity, identity checks, a route to its destination and a way to reconcile exactly what happened. And today, I'm joined by the co-founder and CEO of a company called Noah. And together, we're going to discuss the infrastructure and the business problems that stablecoins are intended to solve. And we'll also talk about where stablecoins can fit alongside existing payment systems,
[00:01:17] why banks remain part of the picture, and how a simpler customer experience can just require work underneath. You will hear more about the opportunities my guest sees, alongside questions about trust, compliance and responsibilities. But if you've ever wondered whether stablecoins need to appear in a customer experience at all, today's conversation will give you a useful way to think about what changes behind the familiar payment screen today
[00:01:44] and have a better understanding of exactly what stablecoins are. But enough from me. Let me introduce you to today's guest. So, a massive warm welcome to the show. Can you tell everyone listening a little about who you are and what you do? Hi, I'm Amir Sharif. I'm the founder and CEO of Noah. We are a stablecoin infrastructure company. We serve over 200 clients from enterprises to smaller companies. And yeah, we've been growing 500% over the last year to date.
[00:02:13] And yeah, it's been a very exciting space so far. Yeah, that success is one of the things that put you on my radar. Set off my tech spidey sensors. And every day on here, I try and demystify an area that people hear about but a little unsure. And stablecoins, I think they're often described as a faster payment rail. But for people listening that are hearing about them for the first time, or know a little about them but not too sure, what problems do they solve better than maybe existing traditional systems?
[00:02:42] Yeah, so maybe take a short back. So, existing traditional systems are heavily reliant on corresponding banking when it comes to cross-border payments. So, you can imagine this in a way where if you want to make a payment from A to B, from one country to another, it goes through a number of hoops and mostly it interacts with a number of banks. Banks have often legacy software, which ends up making a payment delay by three to five days and costs quite high.
[00:03:09] And it's not very intuitive for what the demand is today with everything moving towards agentic payments. You know, everyone is pretty much used to instant, everything to be instant. And stablecoin solves a lot of that. So, you're able to basically move money from A to B, from one country to another or many borders in like little less seconds. And it settles in real time. And then once you connect to local payment methods, you have basically instant global money movement from one currency to another.
[00:03:39] And to bring to life what we're talking about here, probably the best way is to share maybe a customer story. You don't have to name any names, but just something that shows what access to a global financial system changes for a person or indeed a business in real practical terms. Any stories you can share there? So, let's say pick one, right? So, I'm a customer in the US. I want to pay in Argentina. So, normally it would take a few days. It will cost anywhere from 5% to 8%, FX included.
[00:04:09] But now with stablecoins, you have the ability to actually make instant payments. You have the ability to move from US dollar to Argentina pesos or actually settle the person also in US stablecoins, which gives the recipient the option to actually keep dollar because a lot of these currencies around the world are more inflationary towards dollar. So, basically, many, many users from consumers to businesses
[00:04:35] have an interest in naturally keeping stablecoin in their wallet or as a store of value. So, you have these flexibility in one, what currency you want to hold and what exposure you want to have. You have the better speed. You have less fees. So, there's a number of benefits that kind of benefit the user. But also, the other one is traceability. You know exactly what a payment is at any moment in time because they're all tracked. The blockchain is obviously public. Everyone can monitor everything,
[00:05:03] which is pretty good in a way that it gets more transparency to the user. I'm curious, if we were to take a little peek under the hood, what is it that has to happen technically behind the scenes for a stablecoin payment to feel simple when liquidity, settlement, compliance, and local currencies, all these different aspects are involved. What's going on then? So, you have, one, the liquidity components. So, obviously, we have liquidity against any currency to any stablecoin pair.
[00:05:32] This is something that has been basically built up over the last five years with the growth of stablecoins. So, one, you have liquidity components. So, you have to be able to convert US dollar to stablecoins from any local currency to any stablecoin. And then you have the other part, which is the routing. So, every payment gets routed to each choreo or to each partner. And then it weighs the cost of whether this payment is a consumer payment. Is that the partner that we need to use for? And then you have different methods.
[00:06:02] You have different pricing that needs to be taken into consideration. So, we have the routing algorithm that's quite key. Then you have the entire compliance piece, which is obviously a big part of it. Everything has to be done compliantly, but also in a very user-friendly way. Because what we want to avoid is that the user has to KYC multiple times or KYB multiple times in whatever they're going through each partner. So, often, we take the burden of KYC, KYB.
[00:06:31] Our partners are fine with us handling that and are basically operating on a reliance model with us. So, we basically pass on packets of KYC, KYB where needed. We make that super streamlined and make sure that the user doesn't feel that pain. And then you have settlement and reconciliation. So, you have the basic settlement success and then reconciliation part. And yeah, so all of that in a very abstracted way
[00:06:57] that is easy for our partners to plug in without worrying about all these components. Does that make sense? Yeah, it really does. And I suspect that we will have a few critics, and we always will. And some will argue that stable coins can actually add another layer of risk rather than remove friction. And how much of that is exaggerated and how many of those concerns do you think are genuinely justified? Yeah, a lot of these concerns come from back in the days, I guess, crypto and blockchain digital assets.
[00:07:26] In the early days, it was the wild, wild west. But as you can see, you have now regulation in place outlining how stable coins are ought to be regulated. You have that in the US, you have that in Europe, you have many, many jurisdictions. That should give more comfort to users because those products are not regulated in a banking-grade way. So if you look at under the hood, they are very, very rigorous. You have to have certificates, audits on reserves.
[00:07:53] There is a number of liquidity each issuer should basically have just in case there's a lot of redemption. Then a lot of the assets are held in short-term treasury bonds, which are able to be liquidated actually in a very short period of time. So I would say a lot of that has been already now thought through. And with the Genius Act in the US and many other regulatory clarities in other markets, you have that very much pretty much de-risk, I would say. Yeah, completely agree.
[00:08:22] And I'm curious, for people that are listening here and fairly new to this space, how should they decide when a transaction would remain on traditional rails and when that stablecoin route offers a much better outcome? I would say there's two components to it. One is the clients interacting with stablecoin. I think that's one use case. I think there is a growing use case for that. Like many, many new users are very stablecoin native. They understand why it's beneficial, why it's frictionless.
[00:08:51] But of course, you know, some of the people who have been used to older ways of doing payments are not willing to adapt to that fast enough because it's a bit of a friction. They have to learn a new way of moving money. But then the second point is the stablecoin actually happens behind the scene without the user actually noticing. And I think that is obviously a much more growing trend. So I think a lot of users will soon interact with a lot of payment systems that actually have stablecoins in one form or another involved without actually, you know, noticing.
[00:09:21] It's basically like just runs behind the scenes as a more efficient settlement layer. And for people listening in heavily regulated industry, what are the hardest compliance and identity problems when one product serves users across so many different jurisdictions? Any challenges there they should be aware of? Yeah, massive challenges. I think it's super challenging because you are serving a pretty wide market. So we're live in over 140 countries.
[00:09:49] We have different reporting obligations. We have different types of users in every market, you know, and they have their own issues in terms of what they can provide or what they can't provide. Then we have different fraud vectors in every market because in SAP Havans markets, you just experience more fraud. So all of those things have to be taken into consideration. Then all of that has to be done in a very UX friendly way because the users today are extremely demanding. They want everything instant and fast.
[00:10:16] So you have to find the right tools and technology to make sure that you are very rigorous and thorough whilst also keeping the best user experience at all times. So that's kind of a very challenging space. And then you work with regulators and you want to make sure that you align with them. A lot of their concerns are super valid. I think we are totally at the same. But I think it's always like, you know, sometimes there needs some alignment in terms of how the market is moving and innovation is moving. And there they need to also make sure that, you know, obviously we're still aligned with some of the principles of why they have put these regular keywords in place,
[00:10:46] what they want to protect. So it's super challenging because the space is moving fast. And for a company like us to be able to win and grow is just to constantly innovate. And part of that is also making sure we make things better. And today we have so many tools like AI that actually have an impact in how we used to do things. Right in the heart of this space and having so many different conversations with businesses of all sizes, I'm curious, where do stablecoin businesses still depend on banks and other established institutions,
[00:11:15] despite the language of replacing financial infrastructure and being all in on stablecoins? Do you see much there? Yeah. So I think banks will never cease to exist. I think that concept was a wrong one. But I think they will be reorganized in the way of what role they play. So let me clarify this. Banks used to control more and more of the financial system. Let's say the top five banks in the US are pretty much involved in every money payment system.
[00:11:45] There are basically big nodes of the dollar payment system. Every corresponding bank payment will go through them and they make a decision whether they like it or not. So I think that role is getting a bit less. But you also see the trend of now new bank charters being granted where banks are built from a totally new foundation. Some of them are actually blockchain ledgers, stablecoin first, AI first. So what is really a bank? A bank is like a government allowance
[00:12:13] for acting on behalf of the Federal Reserve because you are basically giving dollars and managing that basic currency in a more regulated way. But I think the use case and the role is changing and is forming. And I think that is, I think, most exciting. Banks will always play a role because, again, they are maintaining a subledger of the Federal Reserve and that has a certain regulatory burden. But to what extent there will be involved
[00:12:41] in every payment transaction is probably going to change. And again, for people listening, when payments inevitably become faster and more programmable, any protections they need to be aware of so users don't carry more risk than when something goes wrong than they need to? Anything you can share on protections for them? I think, obviously, work always with very regulated companies that have a strong presence and license. I think that is very important. If you are in a market, like I said, in the US,
[00:13:11] normally your players who are allowed to participate in a market are very regulated. Of course, do your own research. But there's always a lot of trust involved. I think we can't expect users to go and check every smart contract. It's extremely hard. But I think what you can do is really rely on some of the regulatory bodies that exist in order to protect users. All of them have to go to rigorous standards and auditing and testing and to be able to actually offer the service, I would say.
[00:13:40] So that's kind of like a couple of things that would know to like, don't work with very unregulated or slightly gray area operating companies. Try to do your own research in terms of today with Cloud, you can access any information you want, like how the company is set up, their board, like anything matters, the sort of independence and kind of the right people involved. And I think a lot of that is trust. And I think if you want to remove that trust component, then the user has to take
[00:14:08] a lot of burden by themselves, like making sure that the wallets are safe, the stablecoins are working on with safe, as the smart contracts, they're interacting, DeFi. So it's kind of like getting too complicated for the average user. So at the end of the day, I would say it is still the way everything is to work. People trust JP Morgan, people trust all the large banks and the equivalent exists in the stablecoin payments world. Like there are some really big brands and companies, and I think those ones, one should be able to have at least less risk.
[00:14:38] And we are recording this towards the end of 2026, and you've had a phenomenal year. I was reading before you joined me today, 38 million seed, and then you've grown revenue 538% this year. It's phenomenal. Anything you can share on everything that's happened this year and why you're feeling incredibly bullish right now? Yeah, I think the market continues to grow. So we see obviously a further adoption of stablecoin.
[00:15:06] And there are a couple of key drivers. One is massive regular tailwind, especially coming from the US. US has taken a lead to make stablecoin one of the most important national security interests or national interests. I mean, it's very obvious, right? It's like stablecoin grow the last four years by 10x and is at 330 billion market cap, which is the equivalent of having, I think, South Korea, UAE, and Germany together buying the bonds. So you have literally stablecoin issuers
[00:15:35] buying more bonds than most countries. And that is now being pushed by another 10x. So the aim is to get it to 4 trillion by 2030. So you have a huge, it will probably be a top 10 buyer of US debt in the world. So that massive regulatory push behind it, that's going to trickle down in more adoption from banks, fintechs, all sorts of players as there's more clarity coming and support. So that's kind of trickles down and you fall into that virtuous cycle
[00:16:03] where more and more people are buying into it, they're adopting it. And we are just there in the forefront because as companies adopted, they need a payment system. They need all these different tools that we provide. So that's where we benefit from. Wow. I mean, when you look back, I'll just read some stats out here. As we said, 538% increase in annual revenue, 150 plus new customers, revenue 31% month over month, live in 150 markets. Where do you go from here? What can we expect from you guys next year?
[00:16:33] I appreciate you probably locked down and can't share too much, but what's on the horizon? What's next? So I think the product that we have is a kind of a very narrow product in that sense. We are expanding on many different capabilities. We understand the requirements for our clients. We know what our clients are looking for. So there's going to be more products coming to the roadmap. Obviously, as we have been able to grow quite fast, we have more resources and funding and are being able to double down on more engineering, product managers and build those up in a very fast manner.
[00:17:03] We're getting more licenses. And also, yeah, we're closing more and more deals as more bigger enterprises are coming to the market in terms of opportunities. So I think next year, hopefully, it's going to be even a bigger year. Yeah, so far, the foundations are set very well. The team is extremely strong and we continue to double down on hiring great talent. So hopefully next year, it's going to be even greater, yeah. Well, I wish you the best of luck there, but I don't think you need it. It'd be great to get you back on and find out the next chapter and what's happening next and what we can expect.
[00:17:32] So we'll get you back on next year. But for anyone listening, wanting to dig a little bit deeper on all things now and learn more about what you're doing here, I'll include a few links. But anyway, in particular, you would like me to point everyone? Yeah, I think everything pretty much on the website. You'd be imagine magic also, Claude. I mean, you ask a question about a company. It's easy to pretty much be detailed. But I think pretty much everything's public on the website, API docs. And yeah, there's also, I think, a couple of other podcasts, videos. But yeah, that's kind of,
[00:18:01] you find everything on the internet, I guess. Awesome. Well, I'll add a selection of all those links to the blog posts associated with this over at Tech Talks Network. But as I said, best of luck makes you. It'd be great to speak with you again. I've had a phenomenal year this year. Are you going to be taking it easy for over the holiday period or does it just go still? It's not on me, really. I mean, the world is going faster than ever. Like, it feels to me like I wish we could take a break, but it's a race. I mean, AI is driving anything faster. Today, you know,
[00:18:31] people can actually work much more efficiently, but, you know, that it requires certain intensity from certain people. So yeah, sadly not. We're having fun with it. And I think we're living in a very unusual time. And I think we're very lucky to do so. The individual has so much more impact than ever. So let's take full advantage of that. I think we can really change the world for the better. 100% with you. I think it's a beautiful moment to end on. So thanks again. And we'll speak again soon. Thank you so much, Neil. Have a good day. I think one of the many things that will stay with me after this conversation
[00:18:59] is how much work sits behind payments that feel so simple that we all take for granted. A moving value on a blockchain is one part of that process. Converting currencies, checking identities, choosing partners and reconciling the result. All these things still need to happen. But Schott also made the point that banks continue to have a role even as payment infrastructure will continuously develop. And for anyone assessing the space, I would want to understand
[00:19:28] the entire journey, including who holds responsibility when a transfer cannot be completed as expected. Faster movement is undoubtedly valuable, but the experience includes the entry point, the destination and the support along the way. So I will add links to everything that my guest mentioned today around all things Noah. Please check that out and share your thoughts and experiences with me. What would you need to understand before choosing a stable coin route for a business payment across borders?
[00:19:58] As always, techtalksnetwork.com. We have 4,000 interviews over there across eight different podcasts. I'd love to hear from you. Send me a DM, leave me an audio message and we'll keep this conversation going. But we're out of time again, so I will be back again tomorrow with another guest. But thanks for listening as always. Bye for now.